When it comes to figuring out how much auto insurance costs in Massachusetts, it can feel like deciphering a complex puzzle. There are multiple factors at play, from the type of car you drive to your personal driving history. But don’t worry, we’ve got you covered. This guide will break down everything you need to know about auto insurance in the Bay State, so you can navigate your options like a pro.
Massachusetts has its own set of rules and regulations when it comes to auto insurance, making it crucial to understand the essentials. Whether you’re a seasoned driver or a newbie hitting the road, understanding the landscape of auto insurance in Massachusetts will not only save you money but also give you peace of mind. Let’s dive into the specifics and uncover how much you might be spending to stay insured.
Overview of Auto Insurance in Massachusetts
Did you know that Massachusetts ranks among the states with the highest auto insurance rates? That’s right. If you’re driving in the Bay State, understanding your auto insurance options is key to protecting yourself and your wallet.
Auto insurance in Massachusetts isn’t just about following the law—it’s about being prepared. Whether it’s covering damages or medical costs, having the right coverage can save you big time. But what exactly does this coverage entail?
Basic Components of Auto Insurance Coverage
In Massachusetts, auto insurance is divided into several key components. These include Bodily Injury to Others, Personal Injury Protection (PIP), and Damage to Someone Else’s Property. Each of these aspects serves a specific purpose to ensure you’re covered from multiple angles.
Moreover, underinsured and uninsured motorist protections are also important. They shield you against the risk of encountering drivers who don’t have adequate insurance. Here is the deal: without these, you could be left holding the bill.
Legal Requirements for Auto Insurance
Massachusetts drivers are required by law to have auto insurance coverage. This includes a minimum of $20,000 per person and $40,000 per accident for bodily injury, and $5,000 for property damage. It’s not optional; it’s a must.
Failure to comply means hefty fines, potential license suspension, and even vehicle impoundment. So, keeping your policy up-to-date is not just smart—it’s necessary.
Factors Influencing Auto Insurance Rates
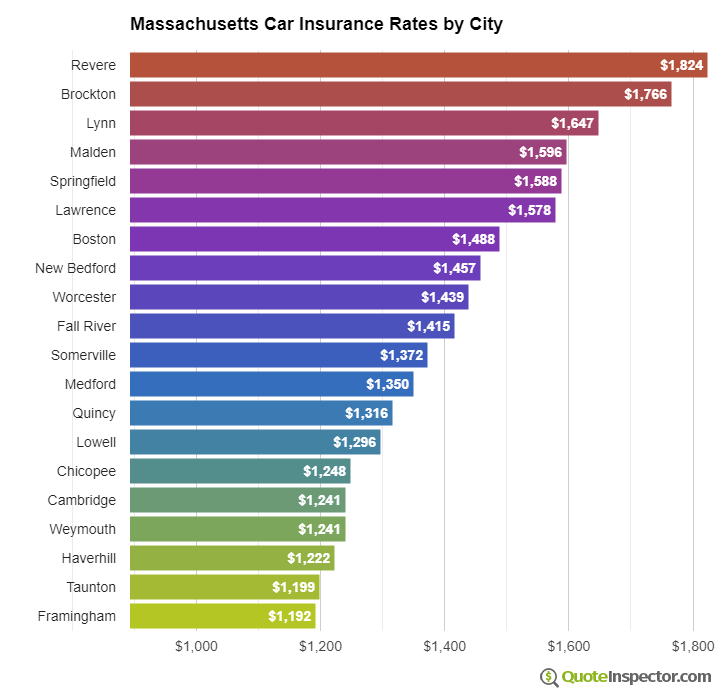
What makes Massachusetts rates so high? A combination of factors such as population density, weather conditions, and accident statistics play a big role. Urban areas, like Boston, naturally see higher rates due to increased traffic and accident likelihood.
However, your personal driving history and credit score can also influence your rates. Insurance companies look at these factors closely when calculating your premiums.
Pro Tip: Maintaining a clean driving record and a good credit score can significantly reduce your insurance costs.
But remember, every insurer calculates risk differently, so shopping around is crucial.
Importance of Having Auto Insurance
Having auto insurance isn’t just a legal obligation—it’s your financial safety net. Imagine getting into an accident without coverage. The out-of-pocket expenses could be astronomical.
Beyond the legal implications, insurance provides peace of mind. Knowing that you’re protected against unforeseen events allows you to drive with confidence.
In short, Massachusetts auto insurance is more than just a requirement. It’s a smart investment in your safety and financial security.
Factors Affecting Auto Insurance Rates in Massachusetts
Did you know that Massachusetts has some of the most varied auto insurance rates in the United States? It’s true, and if you’re wondering why your premium costs an arm and a leg, you’re in the right place.
There are several key factors that determine your auto insurance premium in Massachusetts. From the age of the driver to local regulations, let’s break it down.
Key Factors Determining Premiums
First off, age plays a massive role. Young drivers (under 25) typically face the highest rates due to their lack of driving experience. On the flip side, more experienced drivers tend to enjoy lower premiums. But age isn’t the only factor.
Your driving history is another biggie. If you’ve been in a few fender benders or have a speeding ticket or two, expect your rates to climb. Insurance companies love a clean record, so keep it spotless!
Then there’s your vehicle type. Driving a flashy sports car? Prepare for higher premiums. Economical sedans or family SUVs often get a pass with lower rates.
Local Laws and Regulations
Massachusetts has its own set of rules that influence your insurance rates. The state requires specific minimum coverages that can impact your premiums. Compliance with these laws is non-negotiable, which means you have to factor them into your costs.
Let’s compare these factors in a straightforward way:
| Factors | Description | Impact on Rates |
|---|---|---|
| Age | Younger drivers, especially under 25, face higher premiums. | Significant increase for younger drivers. |
| Driving History | A clean record can drastically reduce your premium. | High impact; clean history lowers rates. |
| Vehicle Type | Luxury and sports cars attract higher insurance costs. | Higher for premium and sports vehicles. |
| Local Regulations | Massachusetts mandates specific insurance coverages. | Moderate; mandatory coverage affects rates. |
Pro Tip: Keep a close eye on your driving record and consider opting for a defensive driving course to potentially lower your premiums.
So, whether you’re a young driver or a seasoned pro, knowing these factors can help you navigate the complex world of auto insurance in Massachusetts.
Average Cost of Auto Insurance in Massachusetts
How much does it really cost to insure your car in Massachusetts? The answer might surprise you. On average, drivers in Massachusetts pay around $1,200 annually for auto insurance. But this number varies widely based on several factors.
Insurance costs fluctuate based on where you live, your age, and what type of car you drive. For instance, a younger driver in Boston driving a sports car will likely pay more than a middle-aged driver in rural Massachusetts with a sedan.
Cost Differences Based on Demographics and Vehicle Types
The cost of auto insurance can change dramatically based on demographics like age and gender. Generally, young male drivers tend to face higher insurance rates compared to any other group. Meanwhile, vehicle type plays a huge role too. SUVs and luxury cars often come with heftier insurance premiums than compact cars or sedans.
Here is the deal: If you live in a city, expect to pay more. Consider this table that shows costs from various cities in Massachusetts:
| City | Minimum Coverage Cost | Full Coverage Cost |
|---|---|---|
| Boston | $1,300 | $2,000 |
| Worcester | $1,100 | $1,800 |
| Springfield | $950 | $1,600 |
| Plymouth | $800 | $1,400 |
Auto Insurance Market Trends in Massachusetts
Over the past few years, the auto insurance market in Massachusetts has seen a steady increase in rates. The good news? This trend is beginning to slow. However, rates are still influenced heavily by factors like the economy and claims history. Insurance companies are increasingly using technology to calculate premiums, which can either help or hurt your wallet depending on your driving habits.
Pro Tip: Install a telematics device in your car to potentially lower your rates if you have safe driving habits.
Tips for Reducing Auto Insurance Costs
Auto insurance in Massachusetts isn’t cheap. BUT you can slash your premiums with some smart moves.
Yes, you can save hundreds on insurance without cutting coverage. Here is the deal: by leveraging discounts and making strategic choices, you can significantly lower your costs.
Identifying Discounts Offered by Insurers
Did you know some discounts can reduce your premium by up to 25%? Step #1: Ask your insurer about every possible discount. They won’t always tell you unless you ask. Step #2: Look for discounts like safe driver, bundling, and loyalty rewards.
The Power of Bundling Insurance Policies
Bundling can be your secret weapon. By combining your auto and home insurance, you might save up to 30% on premiums. Here’s a pro tip: even if you’re renting, bundling renters and auto insurance can still lead to significant savings.
Maintaining a Clean Driving Record
Your driving record is your golden ticket to lower rates. Insurers love drivers with spotless records. Step #1: Avoid tickets and accidents. Step #2: Take a defensive driving course to show you’re serious. This simple action can lead to a 5-10% decrease in your premium.
Comparing Auto Insurance Providers in Massachusetts
Did you know that choosing the right auto insurance provider can save you hundreds of dollars a year? But, not all insurance companies are created equal. Let’s dive into how you can compare and find the best fit for your needs.
When evaluating auto insurance providers, you need to look beyond just the price. Other key metrics include coverage options, customer reviews, and service quality. Here’s the deal: choosing the right provider involves more than just the bottom line.
Key Metrics for Evaluating Auto Insurance Providers
To effectively compare, start by looking at what each company offers in terms of coverage options. Do they cover everything you need? Next, dive into customer reviews to see how current and past customers rate their experiences. Finally, don’t underestimate the importance of claims handling and customer service. A responsive and helpful claims team can make a world of difference.
Here’s a detailed comparison of the top auto insurance providers in Massachusetts:
| Provider | Coverage Options | Customer Reviews |
|---|---|---|
| Provider A | Basic, Comprehensive, Roadside Assistance | 4.5/5 |
| Provider B | Basic, Collision, Uninsured Motorist | 4.1/5 |
| Provider C | Basic, Comprehensive, Rental Car Coverage | 4.7/5 |
The Role of Customer Service and Claims Handling
You might think that price is the only thing that matters, BUT that’s a mistake. Customer service and claims handling play a crucial role in your overall satisfaction with an insurance provider. Imagine this: you get into an accident and need to file a claim. A provider with subpar customer service can make this process a nightmare.
Pro Tip: Always check the provider’s response time and how they handle claims before signing up.
By taking these factors into account, you can choose a provider that not only fits your budget but also supports you when you need it most.
Future Trends in Auto Insurance for Massachusetts Residents
Are you ready for the future of auto insurance? Because it’s coming fast, and Massachusetts drivers are right in the center of a tech-driven revolution. Let’s dive into what’s next in auto insurance for the Bay State.
Massachusetts auto insurance is on the brink of some major shifts. From cutting-edge technology to new regulations, these changes could significantly alter how you shop for and manage your car insurance. Here’s the lowdown on what to expect.
Impact of Telematics on Auto Insurance Policies
Telematics is the game-changer you need to watch. With devices that monitor your driving behavior, insurance companies can offer personalized rates based on how safely you drive. This means that if you’re a cautious driver, you could see lower premiums.
But, there’s a catch. Not everyone is thrilled about the idea of being constantly monitored. The flip side is that more data could mean more accurate risk assessment, which might not always work in your favor. Keep an eye on how local insurers are adopting this tech. It could radically change your insurance bill.
Regulatory Changes on the Horizon
Massachusetts is known for having strict insurance regulations. However, there are potential changes ahead that could affect your pocketbook. New rules focusing on data privacy and the use of AI in risk assessment might soon shape how insurers calculate your costs.
Here’s the deal: if regulators push for more transparency in how rates are set, you might get a clearer breakdown of why your premiums are what they are. This shift could level the playing field for consumers like you.
Autonomous Vehicles: A Potential Game Changer
Autonomous vehicles aren’t just for science fiction movies anymore—they’re real and they’re coming. As these vehicles hit Massachusetts roads, expect a massive shake-up in the auto insurance landscape. Insurers will need to figure out how to handle the liability shift from drivers to manufacturers.
Pro Tip: Keep a close tab on how insurance companies plan to integrate coverage for autonomous features. Early adopters might find themselves with limited options at first, but this is a space that will evolve rapidly.
Conclusion
As you can see, navigating the world of auto insurance in Massachusetts doesn’t have to be a daunting task. By understanding the key factors and staying informed about the latest trends and regulations, you can make smart decisions that save you money and ensure you’re adequately covered. Remember, the right auto insurance policy is not just about cost but also about the peace of mind it provides. So, arm yourself with knowledge, compare your options, and drive with confidence!
Answers to Common Questions
What are the legal requirements for auto insurance in Massachusetts?
In Massachusetts, drivers are required to have a minimum level of coverage, including bodily injury to others, personal injury protection (PIP), bodily injury caused by an uninsured auto, and damage to someone else’s property.
How does my driving history affect my auto insurance rates in Massachusetts?
Your driving history is a significant factor in determining your insurance premiums. Having a clean record can lead to lower rates, while violations or accidents may increase your costs.
Why are auto insurance rates higher in certain areas of Massachusetts?
Rates can vary based on the area due to factors like crime rates, traffic density, and local regulations. Urban areas tend to have higher rates due to increased risk of accidents and theft.
Can bundling insurance policies reduce my auto insurance costs?
Yes, many insurers offer discounts if you bundle auto insurance with other policies, such as home or renters insurance, potentially leading to significant savings.
What emerging trends are affecting auto insurance policies in Massachusetts?
Advancements in technology, like telematics and the rise of autonomous vehicles, are influencing policies by providing more personalized rates and potentially altering risk assessments.
