Let’s face it: insurance can be a mystifying world full of numbers, jargon, and fine print. But what if you could crack the code and discover how to snag the best insurance rates in North Carolina without the hassle? Welcome to your ultimate guide where we demystify insurance rates and unveil the secrets to savings.
Whether you’re a Tar Heel through and through or a newcomer to the state, understanding the ins and outs of North Carolina’s insurance landscape is your ticket to securing unbeatable rates. From geographic nuances to state regulations, this guide is packed with insights that will empower you to make savvy financial decisions.
Understanding Insurance Rates in North Carolina
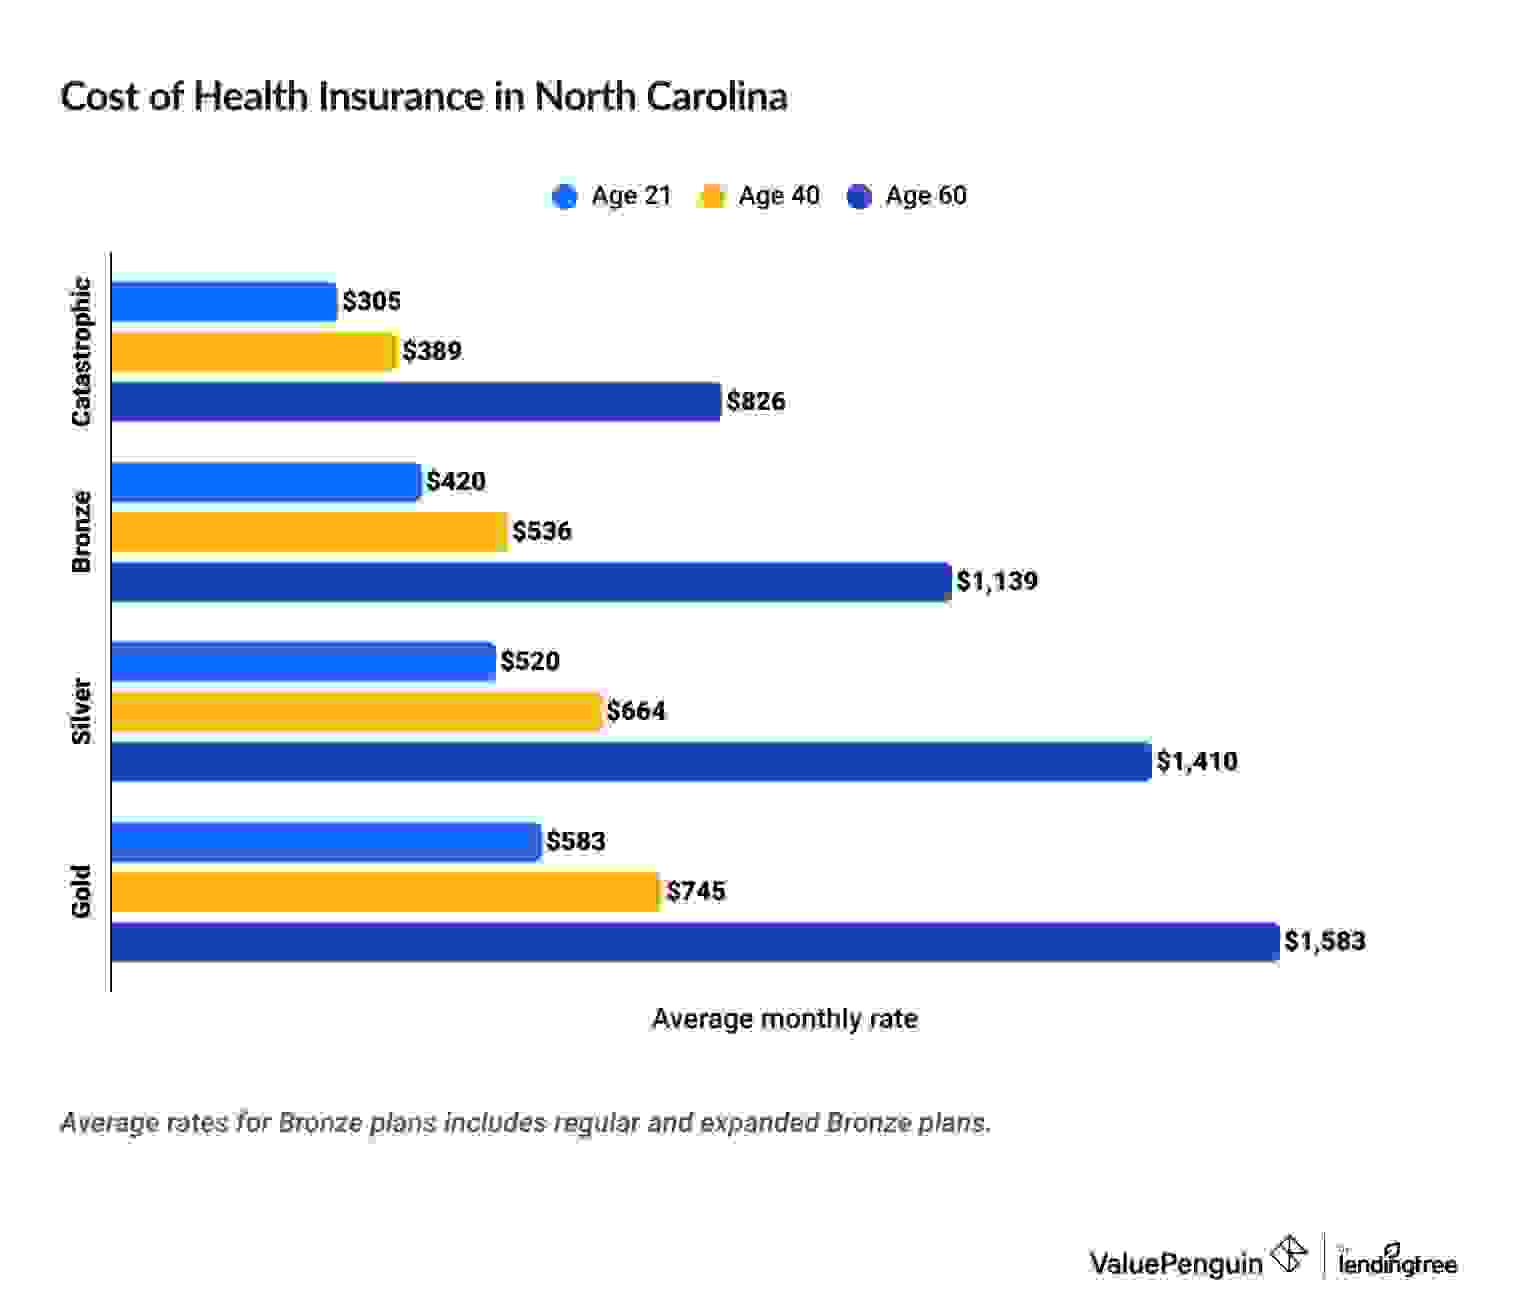
Did you know that your insurance rate can change drastically depending on where you live in North Carolina? It’s true! Rates are influenced by multiple factors that you need to know about.
Insurance rates in NC don’t just appear out of thin air. They are influenced by a mix of state regulations, local factors, and even your street address. But how exactly do these elements weave together to determine what you pay?
Factors Influencing Insurance Rates in NC
Here’s the deal: North Carolina’s insurance rates are affected by more than just your driving record. The state’s regulations and mandates require insurers to consider a variety of elements. This includes your age, car make and model, and even your credit score. But there’s more. Your premium can also be impacted by the type of coverage you choose and the deductible amounts.
- Age and Driving Experience
- Vehicle Type and Usage
- Credit Score
- Cumulative Coverage Options
Pro Tip: Keeping a clean driving record is one of the fastest ways to lower your insurance premium.
State Regulations and Their Impact
Here’s the scoop: North Carolina has a unique insurance regulatory environment. The state’s Rate Bureau has a say in how rates are set and reviewed. This means your insurer can’t just raise your rates because they feel like it—regulations help keep things in check. But it also means you might see less flexibility in rates compared to other states.
- Rate Bureau Oversight
- Mandatory Insurance Requirements
- Legal Constraints on Rate Increases
Because of these regulations, insurers must justify rate changes with detailed data. Knowing this can empower you to question any unexpected hikes.
Geographic Influence on Insurance Rates
Let’s talk geography. Where you live in North Carolina can significantly affect your insurance rates. Urban areas like Charlotte and Raleigh tend to have higher rates compared to rural regions. This is due to increased traffic, higher accident rates, and other risk factors prevalent in city environments.
| Location | Average Annual Premium |
|---|---|
| Charlotte | $1,500 |
| Raleigh | $1,400 |
| Asheville | $1,200 |
So if you’re thinking about moving, it’s worth checking how your new zip code could impact your insurance costs!
Types of Insurance Available in NC
Did you know that the average American spends over $1,200 annually on insurance premiums? In North Carolina, you’ve got a plethora of options to make sure you’re not overpaying. Let’s dive into the types of insurance policies available in the Tar Heel State and how they can benefit you.
Here’s the deal: whether you’re looking to cover your car, your home, or your health, NC offers a wide range of insurance products tailored to your needs. BUT with choices come confusion. It’s crucial to understand what each type brings to the table.
Auto Insurance
Auto insurance is probably the first thing that comes to mind. In NC, you’re legally required to have liability insurance. Beyond that, it’s up to you. Do you want comprehensive coverage that includes theft and natural disasters? Or just basic liability? The choices can be overwhelming.
- Liability Insurance
- Collision Coverage
- Comprehensive Coverage
Pro Tip: Always compare multiple quotes. What works for someone else might not work for you.
Homeowners Insurance
Owning a home is a big deal. So, protecting it should be too. In NC, homeowners insurance covers more than just your house. Think personal belongings, liability protection, and even additional living expenses if disaster strikes.
Step #1: Assess the value of your home and belongings.
Step #2: Choose the best policy that balances coverage and cost.
Health Insurance
Health insurance is non-negotiable. In North Carolina, you have options that range from basic plans to comprehensive coverage. But here’s the kicker: it’s not just about the monthly premium. You must consider deductibles, network restrictions, and out-of-pocket maximums.
| Insurance Type | Coverage Options | Average Rates | Benefits |
|---|---|---|---|
| Auto Insurance | Liability, Collision, Comprehensive | $785/year | Protects against vehicle-related damages and liabilities. |
| Homeowners Insurance | Dwelling, Personal Property, Liability | $1,086/year | Covers property damage and personal liability. |
| Health Insurance | Basic, Comprehensive | $5,280/year | Reduces medical expenses and offers preventive care. |
Don’t let insurance be a headache for you. With the right knowledge, you can secure the best coverage without breaking the bank.
Tips for Finding the Best Insurance Rates
Did you know nearly 70% of people overpay for their insurance? Crazy, right? But don’t worry, because you’re about to learn how to find the best insurance rates in North Carolina.
The process can be intimidating, but understanding a few key strategies can save you a ton of money. Let’s dive into the details.
Guide to Comparing Insurance Rates
To get the best rates, you need to compare quotes from different providers. But here’s the deal: Not all quotes are created equal. You need a strategy.
Start by gathering quotes from at least three insurance providers. Use an online comparison tool to make this process faster and more efficient.
| Provider | Coverage Type | Monthly Premium | Deductible |
|---|---|---|---|
| Provider A | Comprehensive | $100 | $500 |
| Provider B | Comprehensive | $90 | $750 |
| Provider C | Basic | $70 | $1,000 |
Look beyond the price. Compare the coverage details, deductibles, and customer reviews to make an informed decision.
Checklist for Negotiating Better Insurance Rates
Negotiation isn’t just for buying a car. You can negotiate your insurance rates too! Here’s a checklist to help you:
- Review your current policy and identify coverage you don’t need.
- Contact your current provider and ask if they can match or beat a competitor’s quote.
- Inquire about any available discounts (good driver, student, etc.).
- Ask for a higher deductible to lower your monthly premium.
Pro Tip:
Always maintain a good credit score. Insurers often use this as a factor when determining rates.
Strategies to Bundle Insurance Policies for Discounts
Want to save even more? Consider bundling your insurance policies. Many providers offer significant discounts when you combine different types of insurance.
Step #1: List the types of insurance you currently have or need: auto, home, life, etc.
Step #2: Contact your provider to see if they offer a bundling discount. If they don’t, shop around for a provider that does.
Bundling doesn’t just offer savings; it often simplifies your billing and claims process too. It’s a win-win!
Comparing Insurance Providers in NC
Did you know that choosing the right insurance provider in North Carolina can save you hundreds of dollars every year? It’s true. BUT with so many options out there, how do you decide?
Here’s the deal: Not all insurance providers are created equal. Some offer stellar customer service, while others boast competitive rates. Let’s dive into the nitty-gritty of comparing top insurance providers in the Tar Heel State.
Key Players: A Comparative Analysis
When it comes to insurance providers in North Carolina, the market is flooded with choices. However, a few stand out from the rest. Below, you’ll find a table comparing the top players based on customer ratings, coverage options, and price range.
| Provider Name | Customer Ratings | Coverage Options | Price Range |
|---|---|---|---|
| State Farm | 4.5/5 | Auto, Home, Life | $$ |
| Geico | 4.3/5 | Auto, Motorcycle, Renters | $ |
| Nationwide | 4.1/5 | Auto, Home, Pet | $$$ |
| Allstate | 4.0/5 | Auto, Home, Life | $$ |
Customer Service and Claims Processing
When comparing providers, don’t just look at the price. Customer service is crucial. It’s the difference between a headache and a hassle-free experience when filing a claim.
Pro Tip: Call each provider’s customer service line with a simple question. How they respond can tell you a lot about their service quality.
State Farm and Nationwide are known for their prompt claims processing. Geico shines with its budget-friendly options but can be hit or miss with customer service. Allstate balances coverage options with competitive pricing but may lag in claim efficiency compared to others.
Evaluating Customer Reviews and Ratings
Ever wonder if those online reviews are worth your time? 92% of consumers read online reviews before making a purchase. That includes choosing your insurance provider.
Customer reviews and ratings can be a goldmine of information—or a pitfall of confusion. But here’s the deal: not all reviews are created equal. You need to know how to dissect a review like a pro.
Understanding the Importance of Customer Feedback
Why should you care about customer reviews? They offer real-world experiences from folks who were in your shoes. These reviews can reveal hidden fees, annoying customer service, or even unexpected perks. In short, customer feedback can help dodge bullets you didn’t even know were coming.
How to Analyze and Interpret Ratings
Ever stare at a 4.2-star rating and wonder what that actually means? It’s not just about stars. Dive into the comments. Look for recurring themes—both good and bad. If five people mention terrible claims processing, that’s a red flag.
But what about those glowing 5-star reviews? Scrutinize them too. Sometimes, people leave high ratings without detailed comments. Be cautious of overly generic praise like “great service!” with no specifics.
Using Testimonial Quotes for Insight
Testimonial quotes are more than just fluff. They’re user-generated endorsements that can offer unique insights. “This company saved me $200 in premiums for the same coverage” speaks volumes compared to a simple star rating. These nuggets can be your guiding light.
Pro Tip: “Look for patterns in reviews to identify consistent strengths or weaknesses.”
So, next time you’re evaluating an insurance provider in North Carolina, don’t just skim through reviews. Dive deep and read between the lines to find the provider that truly meets your needs.
Exploring Discounts and Special Offers
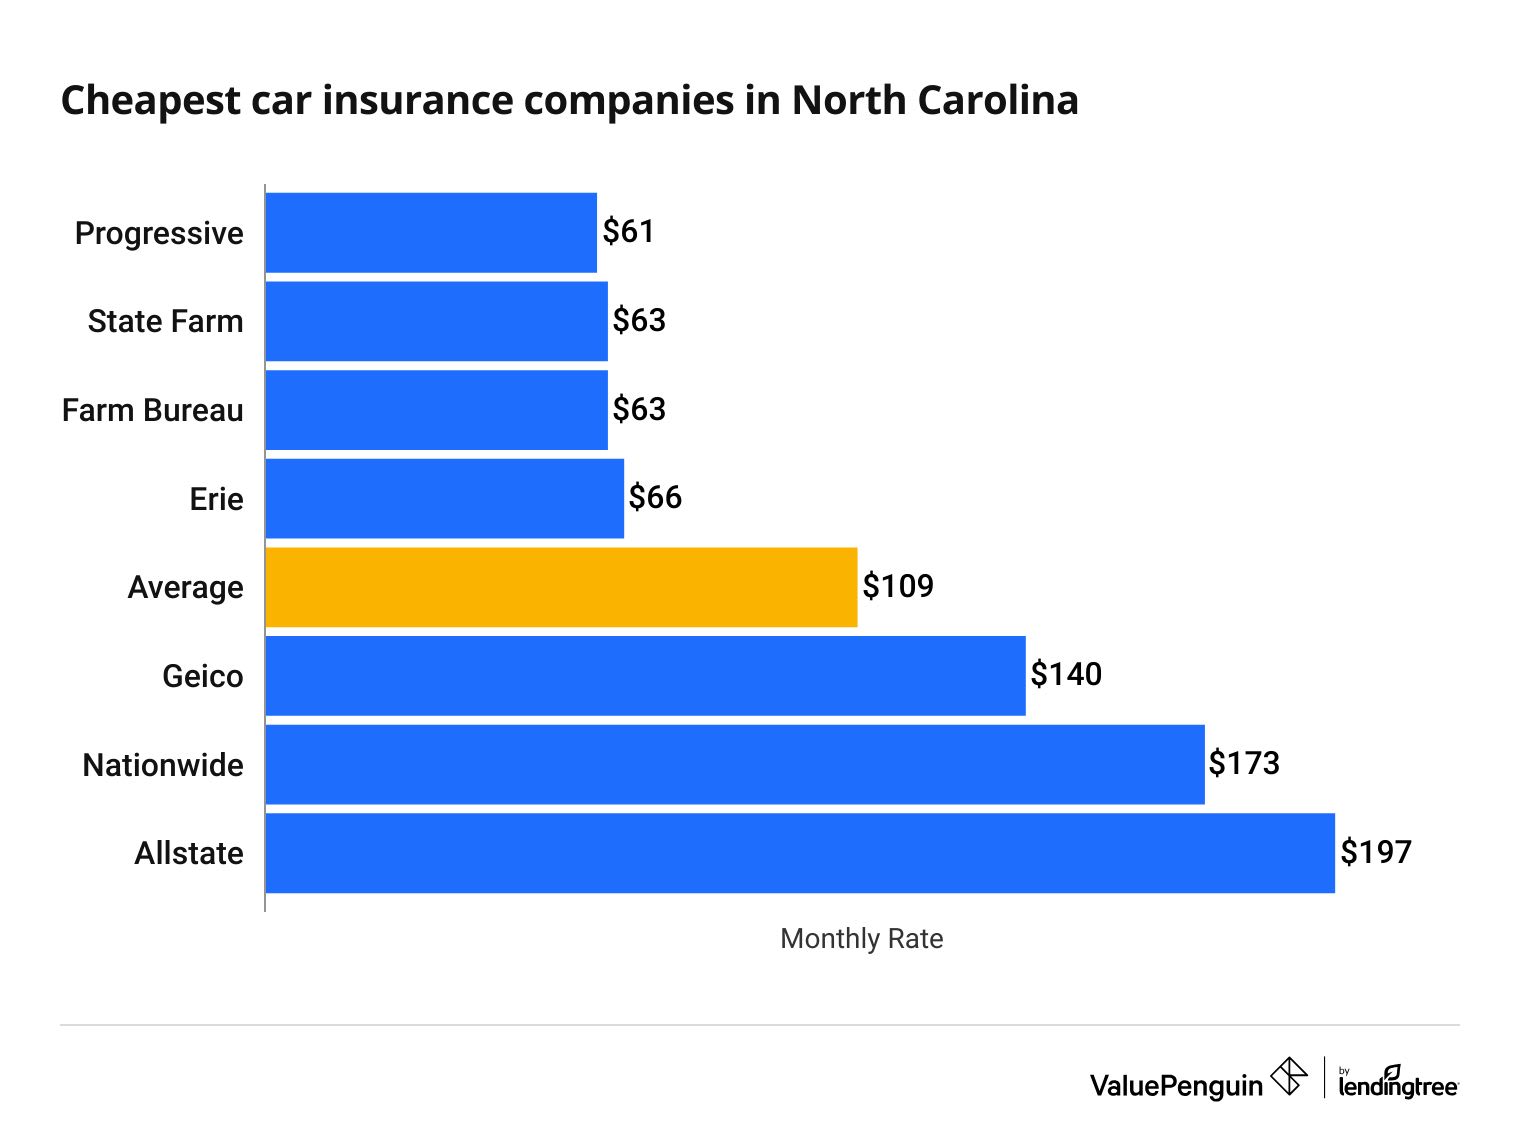
Did you know that over 95% of drivers in North Carolina could be eligible for insurance discounts? That’s a massive opportunity to save money on your policy. Let’s dive into how you can unlock these savings.
Insurance companies offer various discounts that you might qualify for without even knowing it. Whether you’re a safe driver or a loyal customer, there’s likely a discount waiting for you. But here’s the deal: you need to know where to look and how to ask.
Common Discounts Available in North Carolina
In North Carolina, several discounts are available across most insurance providers. For example, safe driver discounts reward you for maintaining a clean driving record. There are also multi-policy discounts if you bundle home and auto insurance. And don’t overlook good student discounts—many insurers offer savings for students with a B average or better.
- Safe Driver Discount
- Multi-Policy Discount
- Good Student Discount
- Low Mileage Discount
- Military Discount
Special Offers from Major Insurance Companies
Major insurers often run special promotions that can lead to significant savings. Allstate occasionally offers a “Drivewise” program, providing discounts for using their mobile app to monitor safe driving habits. Meanwhile, State Farm has the “Steer Clear” program for young drivers, offering a safe driving course and a substantial discount upon completion. Knowing these special deals can save you hundreds.
Qualifying for Discounts and Maximizing Savings
Qualifying for these discounts is easier than you might think. To start, ensure your information is up to date with your insurer. You’d be surprised how many people miss out on savings because of outdated records. Also, don’t be shy—call your agent and ask directly about the discounts you might be eligible for.
Pro Tip: Always ask for a review of your existing policy to identify overlooked discounts.
If you haven’t done so lately, consider requesting a policy review today. A 15-minute call could save you hundreds each year!
Final Summary
In the world of insurance, knowledge is power. By understanding the factors that influence rates, exploring various policy options, and leveraging discounts, you’re well on your way to securing the best insurance rates in North Carolina. So dive in, do your homework, and watch your savings grow. Remember, the best rates aren’t just about cost—they’re about getting the coverage that fits you like a glove.
Q&A
What factors influence insurance rates in North Carolina?
Insurance rates in NC are influenced by factors such as your geographic location, driving history, credit score, and the type of coverage you choose.
What types of insurance are available in North Carolina?
North Carolina offers a variety of insurance options including auto, home, health, and life insurance, each with different coverage options and rates.
How can I find the best insurance rates in NC?
To find the best rates, compare quotes from multiple providers, consider bundling policies for discounts, and negotiate with insurers for better rates.
Why is my insurance rate higher than others in NC?
Your rate may be higher due to factors like your location, claim history, or the specific coverage and deductibles you have chosen.
How can I qualify for insurance discounts in NC?
To qualify for discounts, maintain a good driving record, improve your credit score, and inquire about special offers when bundling policies.
